
Alterations for equipment
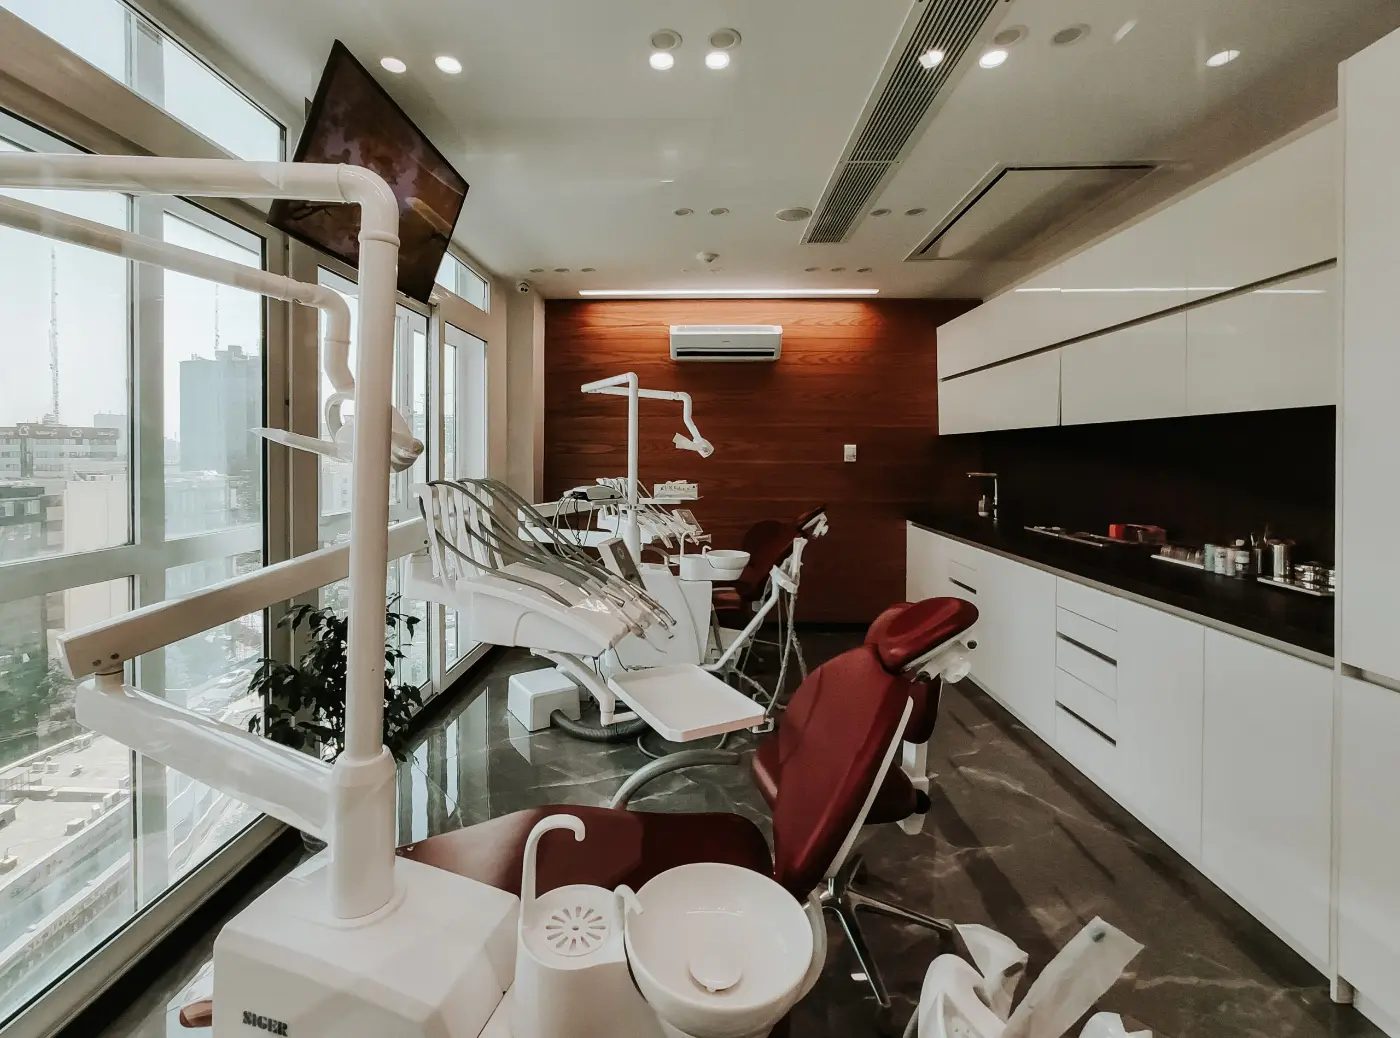
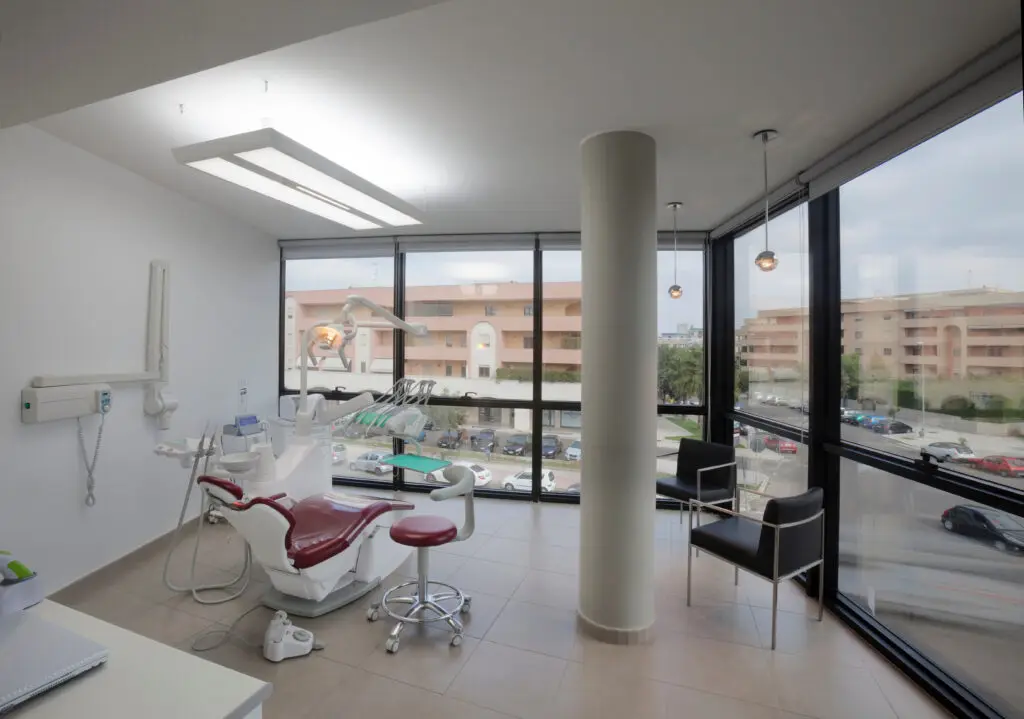
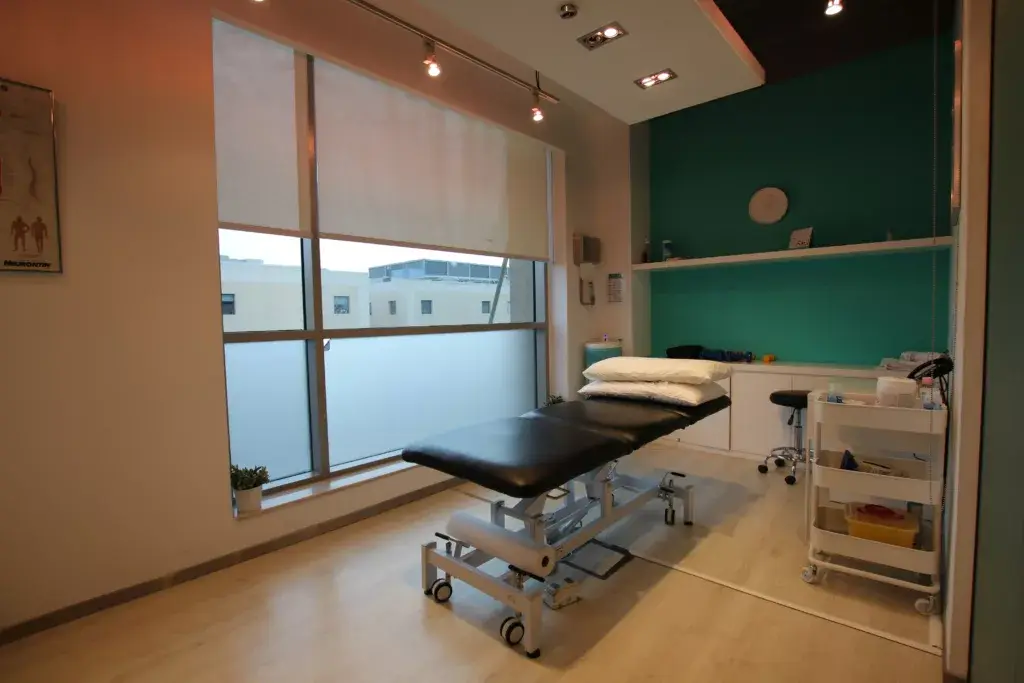
s25 CAA 2001Work to the building that is incidental to installing plant, such as strengthening floors or adapting rooms for imaging and dental equipment, can be claimed alongside it.
Capital allowances for medical surgeries
Nurse call alarms, ventilation, specialist electrical installations, partitioning and reception fit-outs qualify. We typically find 23% of the purchase price.
Medical buildings are services-heavy: ventilation for treatment rooms, dedicated electrical circuits for equipment, nurse call systems and accessible facilities. Practice owners often don’t realise how much of that qualifies.
We typically identify about 23% of the original purchase price. On a £550,000 surgery that is around £126,000 of allowances and roughly £50,000 in tax relief for a higher-rate partner.
If you own the premises personally, through a partnership or a company and pay UK tax, you can claim. A typical claim takes about six weeks from first meeting to relief.
What qualifies
Legislation that matters
Work to the building that is incidental to installing plant, such as strengthening floors or adapting rooms for imaging and dental equipment, can be claimed alongside it.
GP and dental partnerships of individuals cannot use full expensing. The 40% first-year allowance from 1 January 2026 gives them an accelerated route on new equipment beyond the £1m AIA.
Writing down allowances on the main pool fell from 18% to 14% from April 2026. Claiming AIA on qualifying fixtures, rather than leaving them in the pool, matters more than it did.
Recent medical surgeries claims
The UK’s leading capital allowance specialists
Embedded allowances need a property survey, a valuation and specialist tax knowledge. Most accountancy firms claim invoiced items such as furniture and computers, but don’t have the surveying resource to identify fixtures built into the fabric of a building.
Allowances are not deducted from the cost of the asset when calculating a gain (s41 TCGA 1992), so a claim cannot create or increase a chargeable gain. They can restrict a capital loss, and on a sale the s198 election decides what passes to the buyer, so plan it into the transaction.
Every claim is documented to stand up to scrutiny, and we support you throughout any HMRC enquiry. To date every report we have submitted has been approved.
No. If we can’t identify previously unclaimed allowances, there is no fee. Full fee terms are set out in our engagement letter.
Two minutes, no obligation, and no fee if we can’t identify previously unclaimed allowances.