Your hotel is full of tax relief nobody has claimed
Commercial kitchens, lifts, guest bathrooms and the air conditioning in every room are plant under the Capital Allowances Act 2001. We find them, value them and claim them.
Whether you run a boutique guesthouse or a franchised hotel, the building you bought came with fixtures that qualify for tax relief. They sit inside the purchase price, unidentified, until a surveyor and a tax specialist separate them out. Most general accountants never do this, because it needs a site survey and a valuation as well as the tax knowledge.
We have done it for hundreds of hotels across the UK, including properties in the Marriott and Hilton groups. On average we identify around 32% of the original purchase price as qualifying expenditure. On a £1m hotel that is roughly £320,000 of allowances, worth about £128,000 in tax relief for a higher-rate taxpayer: money for refurbishment, staff training or the next acquisition.
The process typically takes six weeks from first conversation to relief from HMRC, and we deal with HMRC on your behalf. If we can’t identify previously unclaimed allowances, there is no fee.
Typical claim
Hotels bought for £1,000,000
Share typically unclaimed
32%
Capital allowances
£320,000
Relief for a 40% taxpayer
£128,000
Illustration only. Companies pay corporation tax at up to 25%, so relief would be lower.
What qualifies
Items we claim in hotels
Lifts
Heating and radiators
Air conditioning
Electrical and lighting systems
Commercial kitchens
Bathroom and en-suite fittings
Kitchenettes
Security systems and CCTV
Fire alarms
Decor that creates ambience
Main rate pool (14%) or AIAIntegral feature: special rate pool (6%) or AIA
Legislation that matters
The rules and cases behind a hotel claim
Ambience can be plant
Scottish & Newcastle Breweries v Lord Advocate [1982]
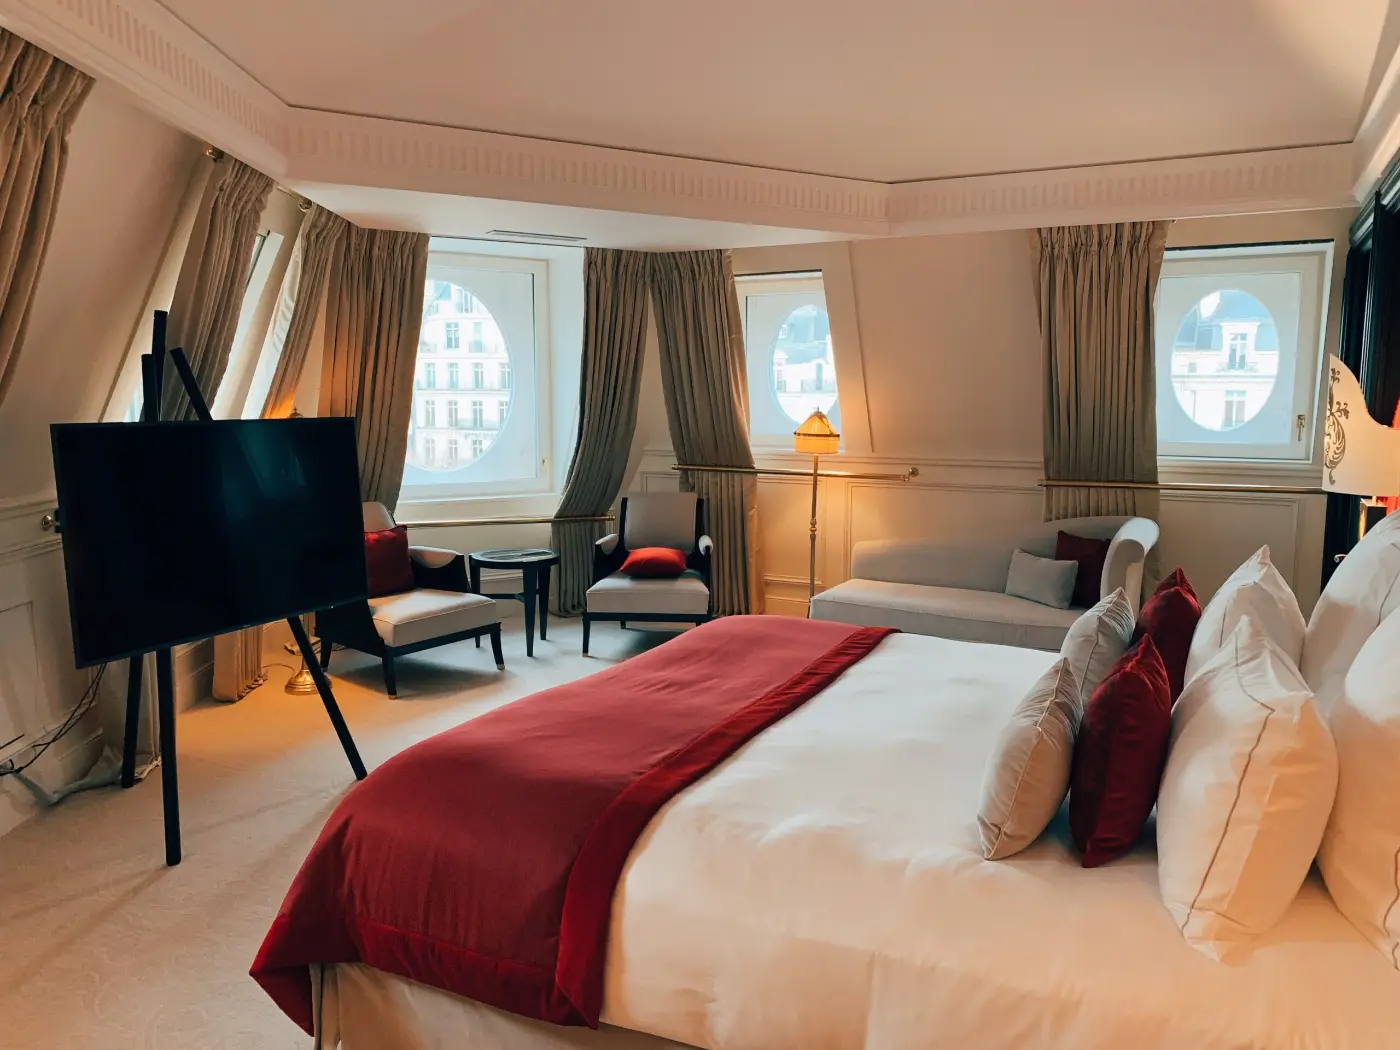
The House of Lords accepted that murals, decorative light fittings and other items installed to create a hotel’s atmosphere were plant, because creating that setting is part of the trade. It is the reason a hotel survey goes beyond the boiler room.
Integral features pool
s33A CAA 2001
Lifts, electrical and lighting systems, cold water, space and water heating, and air conditioning are integral features. They go into the special rate pool at 6% a year, unless the Annual Investment Allowance absorbs them first.
Buying a hotel: fix the value
s187A, s198 CAA 2001
Since April 2014 a buyer can only claim fixtures if the seller pooled them and the value is fixed, usually by a joint s198 election within two years of completion. Bring us in before exchange and the contract protects your allowances.
Hotels are not dwelling-houses
s35 CAA 2001
The dwelling-house restriction that blocks allowances in residential lets does not apply to hotel bedrooms. That distinction became sharper when the furnished holiday let regime ended in April 2025.
Embedded allowances need a property survey, a valuation and specialist tax knowledge. Most accountancy firms claim invoiced items such as furniture and computers, but don’t have the surveying resource to identify fixtures built into the fabric of a building.
Does a claim affect Capital Gains Tax?
Allowances are not deducted from the cost of the asset when calculating a gain (s41 TCGA 1992), so a claim cannot create or increase a chargeable gain. They can restrict a capital loss, and on a sale the s198 election decides what passes to the buyer, so plan it into the transaction.
What if HMRC questions my claim?
Every claim is documented to stand up to scrutiny, and we support you throughout any HMRC enquiry. To date every report we have submitted has been approved.
Are there any hidden costs?
No. If we can’t identify previously unclaimed allowances, there is no fee. Full fee terms are set out in our engagement letter.