Industrial property: relief on the building, the fit-out and the kit
Security shutters, lighting, fire systems, welfare facilities and process-related services qualify, and new builds open up full expensing and the Structures and Buildings Allowance.
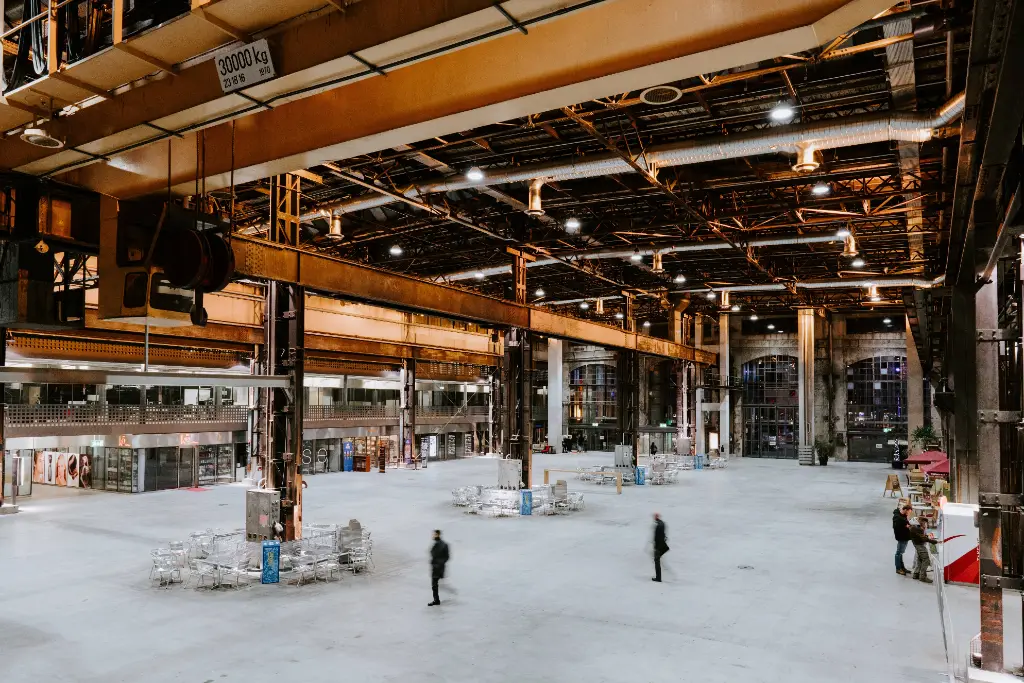
Factory and warehouse owners rarely realise how much relief their buildings hold. Security shutters, lighting, fire alarms, kitchen and bathroom facilities and the power supply to machinery all count.
On acquisitions we typically identify around 15% of the original purchase price. On an £800,000 unit that is £120,000 of allowances and about £48,000 in tax relief for a higher-rate taxpayer. New construction, fit-out and refurbishment projects produce much higher percentages.
We work alongside your accountant, survey the site with minimum disruption and handle everything with HMRC.
Typical claim
Industrial bought for £800,000
Share typically unclaimed
15%
Capital allowances
£120,000
Relief for a 40% taxpayer
£48,000
Illustration only. Companies pay corporation tax at up to 25%, so relief would be lower.
What qualifies
Items we claim in industrial
New construction
Fit-out works
Refurbishment works
Specialist equipment and process services
Electrical power and lighting
Security shutters and automatic doors
Welfare, kitchen and bathroom fittings
Moveable cabins and temporary buildings
Main rate pool (14%) or AIAIntegral feature: special rate pool (6%) or AIA
Legislation that matters
The rules and cases behind an industrial claim
Where the building ends
Urenco Chemplants v HMRC · Court of Appeal, 2025
The Court of Appeal held that most of a specialist nuclear facility was a building under s21 and s23, even though it was essential to the trade. Specialist does not mean plant: the claim has to identify the items that perform a function.
40% first-year allowance
Autumn Budget 2025
From 1 January 2026, new main-rate plant attracts a 40% first-year allowance, including assets bought for leasing and spend by partnerships and sole traders who cannot use full expensing.
Structures and Buildings Allowance
s270AA CAA 2001
New warehouses and factories earn 3% of construction cost a year for 33⅓ years. Separating the SBA shell from qualifying plant is where most of the value is won or lost.
Embedded allowances need a property survey, a valuation and specialist tax knowledge. Most accountancy firms claim invoiced items such as furniture and computers, but don’t have the surveying resource to identify fixtures built into the fabric of a building.
Does a claim affect Capital Gains Tax?
Allowances are not deducted from the cost of the asset when calculating a gain (s41 TCGA 1992), so a claim cannot create or increase a chargeable gain. They can restrict a capital loss, and on a sale the s198 election decides what passes to the buyer, so plan it into the transaction.
What if HMRC questions my claim?
Every claim is documented to stand up to scrutiny, and we support you throughout any HMRC enquiry. To date every report we have submitted has been approved.
Are there any hidden costs?
No. If we can’t identify previously unclaimed allowances, there is no fee. Full fee terms are set out in our engagement letter.