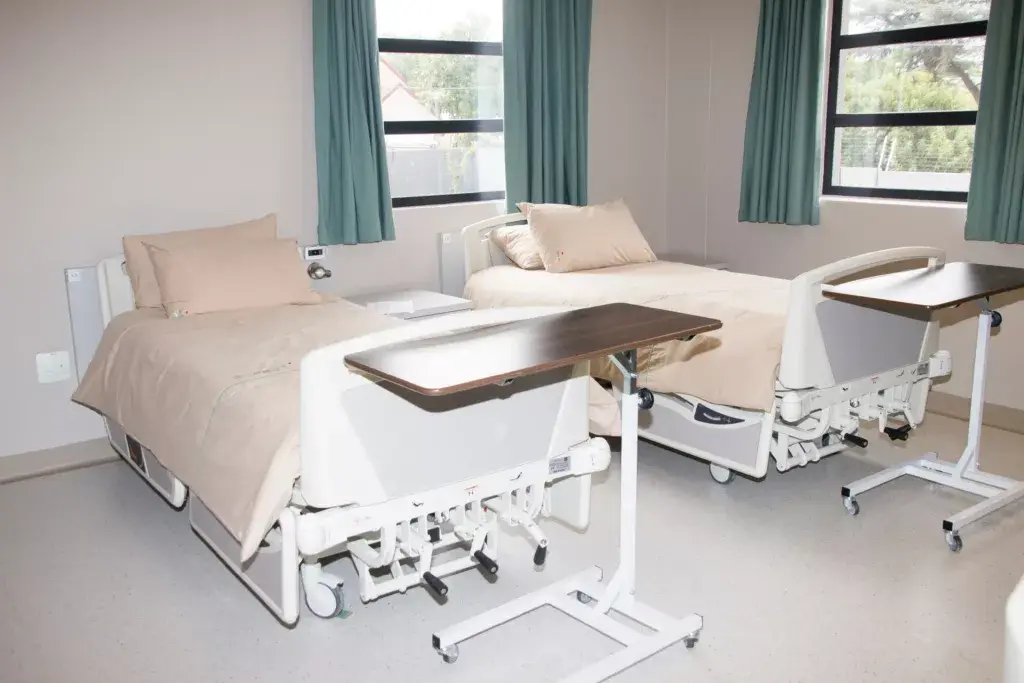
A care home is built around equipment: passenger lifts, assisted bathing, nurse call and fire safety systems, catering kitchens and heating that runs around the clock. Much of that qualifies as plant and machinery, and on purchase it is usually left unclaimed inside the price.
We typically identify around 35% of the original purchase price in previously unclaimed allowances. On a £1m home that is £350,000 of allowances and around £140,000 in tax relief for a higher-rate taxpayer.
If you own a care home and pay UK tax, you can claim. Our in-house surveyors and chartered tax specialists work only on capital allowances, and relief typically arrives about six weeks after our first meeting.
Typical claim
Care Homes bought for £1,000,000
Share typically unclaimed
35%
Capital allowances
£350,000
Relief for a 40% taxpayer
£140,000
Illustration only. Companies pay corporation tax at up to 25%, so relief would be lower.
What qualifies
Items we claim in care homes
Passenger and bed lifts
Heating and radiators
Air conditioning
Hot and cold water systems
Nurse call and alarm systems
Assisted bathroom fittings
Commercial kitchens and laundries
Fire alarms and fire doors hardware
Security systems
Main rate pool (14%) or AIAIntegral feature: special rate pool (6%) or AIA
Legislation that matters
The rules and cases behind a care home claim
Not a dwelling-house
s35 CAA 2001 · HMRC Capital Allowances Manual
HMRC’s own guidance treats care homes and similar communal residential buildings as outside the dwelling-house restriction, so fixtures in residents’ rooms qualify alongside the communal areas.
Use the £1m AIA on acquisition
s51A CAA 2001
The Annual Investment Allowance is permanently set at £1m and, unlike full expensing, is not limited to new assets. On one £3.2m care home purchase it let our client claim £1.23m of allowances and receive a first-year benefit of £492,800.
Fixtures need pooling before sale
s187A CAA 2001
Care homes change hands often. If the seller never pooled the fixtures, the buyer can lose the allowances for good. A s198 election agreed in the sale contract prevents that.
Embedded allowances need a property survey, a valuation and specialist tax knowledge. Most accountancy firms claim invoiced items such as furniture and computers, but don’t have the surveying resource to identify fixtures built into the fabric of a building.
Does a claim affect Capital Gains Tax?
Allowances are not deducted from the cost of the asset when calculating a gain (s41 TCGA 1992), so a claim cannot create or increase a chargeable gain. They can restrict a capital loss, and on a sale the s198 election decides what passes to the buyer, so plan it into the transaction.
What if HMRC questions my claim?
Every claim is documented to stand up to scrutiny, and we support you throughout any HMRC enquiry. To date every report we have submitted has been approved.
Are there any hidden costs?
No. If we can’t identify previously unclaimed allowances, there is no fee. Full fee terms are set out in our engagement letter.