
Alterations to install plant
s25 CAA 2001Building work that is incidental to installing plant, such as forming a changing area around new sanitaryware, can be claimed with the plant itself. Nursery conversions usually contain a lot of it.
Capital allowances for childcare
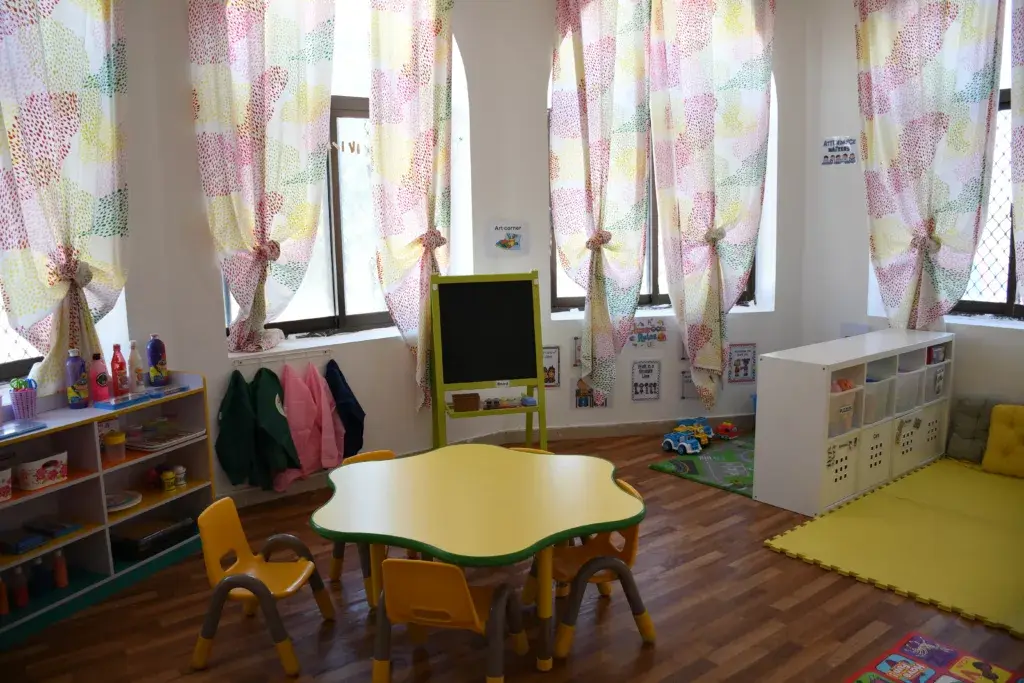
Safety gates, window restrictors, accessible bathrooms, automatic doors and specialist equipment all qualify, as do moveable classrooms.
Nursery owners are often unaware that their building holds thousands of pounds in unclaimed relief. Air conditioning, wiring, plumbing and the safety equipment Ofsted expects are plant and machinery or integral features.
Depending on the property’s tax history, allowances are usually worth 20% to 40% of the acquisition price. If you have remodelled or fitted out recently, that rises sharply: 70% to 90% of the cost of the works can qualify.
Our in-house team works only on capital allowances. On average relief arrives about six weeks after our first meeting, and there is no fee if we can’t identify previously unclaimed allowances.
What qualifies
Legislation that matters
Building work that is incidental to installing plant, such as forming a changing area around new sanitaryware, can be claimed with the plant itself. Nursery conversions usually contain a lot of it.
Moveable buildings intended to be moved in the course of the trade sit in List C, so temporary classrooms and cabins can qualify where the building restrictions would otherwise apply.
Nursery groups trading through a company can deduct 100% of new main-rate plant in the year of spend, with no upper limit. Full expensing was made permanent in November 2023.
Recent childcare claims
The UK’s leading capital allowance specialists
Embedded allowances need a property survey, a valuation and specialist tax knowledge. Most accountancy firms claim invoiced items such as furniture and computers, but don’t have the surveying resource to identify fixtures built into the fabric of a building.
Allowances are not deducted from the cost of the asset when calculating a gain (s41 TCGA 1992), so a claim cannot create or increase a chargeable gain. They can restrict a capital loss, and on a sale the s198 election decides what passes to the buyer, so plan it into the transaction.
Every claim is documented to stand up to scrutiny, and we support you throughout any HMRC enquiry. To date every report we have submitted has been approved.
No. If we can’t identify previously unclaimed allowances, there is no fee. Full fee terms are set out in our engagement letter.
Two minutes, no obligation, and no fee if we can’t identify previously unclaimed allowances.